Withholding Tax Credit Monitor for Czech Stock Income Investors
Emily CarterMost people who invest in dividend stocks and ETFs eventually run into the same frustrating situation: their income is spread across several brokers, paid in different currencies, on different dates, and each payment arrives already reduced by a different amount of withholding tax. Trying to make sense of that with a spreadsheet works for a while, then quietly stops working. This article explains why dividend income gets lost in the gaps between brokers, what a serious dividend tracker should actually do, and how the foreign withholding tax credit fits into the picture for Czech tax residents. Veverio is one example of a tool built around this exact problem, and the principles below apply whichever tool you choose.
Why Dividend Income Gets Lost Across Brokers and Currencies
A dividend is simple in concept: a company distributes part of its profit to shareholders. In practice, every payment carries a set of attributes that vary from one holding to the next. It arrives in the currency of the listing or the currency the broker settles in, it is paid on a date that may differ from the declared schedule, and it is usually net of some withholding tax that depends on the country of the issuer and the country of the investor. Multiply those variables by three or four brokers and a portfolio of thirty positions, and the number of distinct cash events in a single year can easily run into the hundreds. Before comparing payouts across holdings, many investors keep a dividend tracker that records each payment's currency, ex-date, pay date, and the amount actually received after withholding.
- One that calculates foreign withholding credits, respects the relevant treaty framework, and shows its working is considerably more valuable for anyone who must file
- You should be able to trace any figure back to its source payment, override an entry when you have better information, and export the data in a usable format
- The core problems are consistent currency treatment, reliable reconciliation of gross, withholding, and net amounts, accurate instrument mapping, and forecasts that are honest about their limits
- Whatever tool you use, the test is the same: can you trace every figure to its source, explain the method behind it, and defend it to a tax authority
The first thing that breaks in a manual process is currency consistency. A dividend of 12 USD received on a Monday and a dividend of 9 EUR received on a Thursday cannot be summed directly, and the exchange rate you choose changes the result. If you convert at the transaction date, you get one answer; if you use a period average, you get another. Neither is wrong, but mixing the two methods across months makes historical comparisons meaningless. Good tracking forces a consistent policy and records it, so that the numbers you see in March can be compared with the numbers you see in November.
The second thing that breaks is reconciliation. Brokers report dividends in statements that do not line up neatly with each other. One may show the gross amount with the withholding listed on a separate line, another may show only the net cash credit, and a third may book a correction months later. A dividend that was reversed, a payment that was split between two accounts, or a stock that was transferred between brokers can all produce duplicate or missing entries. Without a systematic way to match each payment against the underlying holding and the ex-dividend date, errors accumulate silently.
The real cost of this fragmentation is not just untidy records. It is missed tax credits, forecasts that drift away from reality, and tax that is paid twice or never reclaimed. Those costs are invisible until a filing deadline arrives, which is precisely why they are so easy to ignore.
Where Dividend Data Actually Lives
Dividend information originates in corporate action notices, which announce the declared amount, the record date, the ex-dividend date, and the payment date. Brokers then translate those notices into account entries, and the entries appear in trade confirmations, periodic statements, and sometimes in separate tax reports. Each layer uses its own format, and the timing can differ. An ex-dividend date determines who is entitled to the payment; the payment date determines when cash actually arrives. For reporting purposes, which of the two dates you use can move income from one tax period into another, so a tracker needs to make the distinction explicit rather than collapsing both into one column.
Reconciling the three components of a dividend is the next step. The gross dividend is the amount the company declared per share multiplied by your holding. The withholding is the portion retained by the paying country or the broker before payment. The net is what reaches your account. When these three figures are captured separately and checked against each other, you can spot a mismatch immediately, for example when a broker has applied a higher withholding rate than the treaty would allow. When they are merged into one number, that discrepancy disappears from view.
Ticker symbols add another layer of difficulty. The same company may trade on several exchanges under different tickers, and a fund may be identified by ISIN in one system and by a local code in another. A tracker that maps instruments reliably, using ISIN as the anchor where possible, prevents the same holding from being counted twice or dropped from the forecast entirely.
What Readers Need From a Tracker
Investors who manage income across several accounts generally need the same handful of outputs, regardless of their level of sophistication. They want a consolidated view that shows what was received by broker, by currency, and by calendar month, so that they can see patterns and gaps. They want a forward-looking estimate of upcoming payouts, which is useful for budgeting and for deciding whether to reinvest. And they want records that can be exported cleanly when a tax return is due.
Beyond those basics, the features that matter most are the ones that remove manual work without hiding the underlying data. A good tracker lets you drill down from a monthly total to the individual payment, and from the payment to the corporate action that generated it. If you cannot trace a figure back to its source, you cannot trust it when it matters.
A dividend total you cannot trace back to its source is an estimate, not a record. Good tracking is about keeping that trail intact from the broker statement to the final figure.
How a Dividend Tracker Consolidates Multi-Broker Income
Consolidation begins with getting data in. Most tools accept some combination of CSV exports from brokers, direct connections through an API where the broker supports one, and manual entry for anything that falls outside those channels. CSV imports are reliable but require the file format to be parsed correctly; API connections are faster and update automatically, but they depend on what each broker exposes. Manual entry is a fallback that should be used sparingly, since every manual figure is a point where error can enter the record.
Once data is imported, instruments need to be mapped. The tracker has to recognise that a payment labelled with one ticker and a holding labelled with another refer to the same security. Corporate actions complicate this further. A stock split changes the number of shares you hold and the per-share dividend; a merger may replace one instrument with another; a special dividend arrives outside the regular schedule and can distort a monthly comparison if it is not flagged. A tracker that handles these events explicitly keeps the historical series coherent.

Currency normalisation is the step that turns a collection of payments into a comparable dataset. You choose a base currency for reporting, then convert each payment using a documented rate policy. Transaction-date rates reflect the actual exchange at the moment of receipt and are the most precise, while period-average rates smooth out short-term volatility and are easier to explain in a summary. Either approach is defensible; what matters is applying it consistently and being able to say which one was used.
The dashboard that results should show income by month, by broker, and by currency in a single reconciled view. Duplicate detection is essential here: the same payment can appear in two statements if one broker re-reports it, and a tracker that counts both will overstate income. Reconciling the tracker's totals against each broker's own annual summary is a useful final check, and any difference should be investigated rather than explained away. For anyone who may need to justify the figures later, an audit trail showing where each entry came from is not optional.
Dividend Forecasting Methods and Their Limits
Forecasting dividend income is useful, but it rests on assumptions that deserve to be stated plainly. The most reliable input is a declared dividend, where the company has announced an amount and an ex-dividend date. Forecasts built on declared figures are short-term and grounded in confirmed events, though they still have to account for the possibility that a company changes its policy, cuts a payout, or suspends one entirely. Currency drift matters too: a dividend declared in a foreign currency will be worth more or less in your base currency depending on how the exchange rate moves before payment.
For longer horizons, forecasts usually rely on historical patterns. A trailing twelve-month figure gives a simple baseline, and payout frequency, whether quarterly, semi-annual, or annual, indicates when income is expected to arrive. Seasonality and irregular payers are where averages mislead. A fund that pays a large distribution in December will show a strong December and a weak rest-of-year if you average it naively, which can make monthly budgeting look far more predictable than it really is. A better approach is to forecast per instrument, using each holding's own payment calendar, and then sum the results. Because the figures in such a record are only useful when they are consistent, a dividend tracker helps separate the gross yield a company declares from the cash that ultimately lands in the account.
Communicating uncertainty is part of doing forecasts honestly. Presenting a single number implies more certainty than exists. A range or a confidence band, even a simple one, tells the reader how much the estimate could plausibly move. The forecast should be treated as informational rather than a promise, because companies can and do change their dividends.
Scenario modelling extends the forecast to portfolio changes. If you plan to buy more of a holding, sell a position, or reinvest proceeds, you can project how the income profile changes. Sensitivity to currency movements is worth modelling for any holding whose dividends are paid in a currency other than your base currency. It is also sensible to define thresholds, such as a change in a holding's payout or a significant exchange-rate move, at which the forecast should be re-run rather than left to age.
Foreign Withholding Tax Credits: Mechanics for Czech Tax Residents
Withholding tax is deducted at source. When a company in one country pays a dividend to a shareholder in another, the paying country usually retains a percentage before the money leaves. That rate is set by domestic law and often reduced by a double tax treaty between the two countries. In practice, the amount withheld can be higher than the treaty rate until relief is claimed, which means the investor may initially receive less than the treaty entitles them to. Brokers differ in whether they apply treaty relief at source or leave the investor to reclaim the difference later, and that difference affects both cash flow and the paperwork required.
For a Czech tax resident, the principle is that foreign dividend income is part of the Czech tax base, and the foreign tax already withheld is credited against the Czech tax due on that income. The aim is to avoid taxing the same income twice without simply ignoring the tax that was already paid abroad. The credit is capped, so it cannot exceed the Czech tax attributable to that particular income. Working through that cap requires knowing the gross amount, the foreign tax withheld, and the Czech rate applicable to the income, and doing it separately for each country where income arose.
Documentation is what makes the credit defensible. The records you need include the dividend statements that show the gross amount and the withholding, proof of the foreign tax actually paid, and the exchange-rate records used to convert everything into Czech crowns. Missing any of these means the credit may be disallowed or difficult to substantiate, even when the underlying entitlement is clear.
Doing this by hand is possible for a small number of payments but becomes error-prone quickly. Each dividend has to be mapped to its source country and the treaty rate that applies, the credit has to be aggregated per country and per tax year, and the cap has to be checked for each group. A tool that performs these steps automatically, per payment and per country, reduces the chance of an arithmetic or classification mistake. It does not remove the need to verify the output, and it should be checked against professional advice or the guidance of the tax authority, because treaty rates and filing requirements change over time.
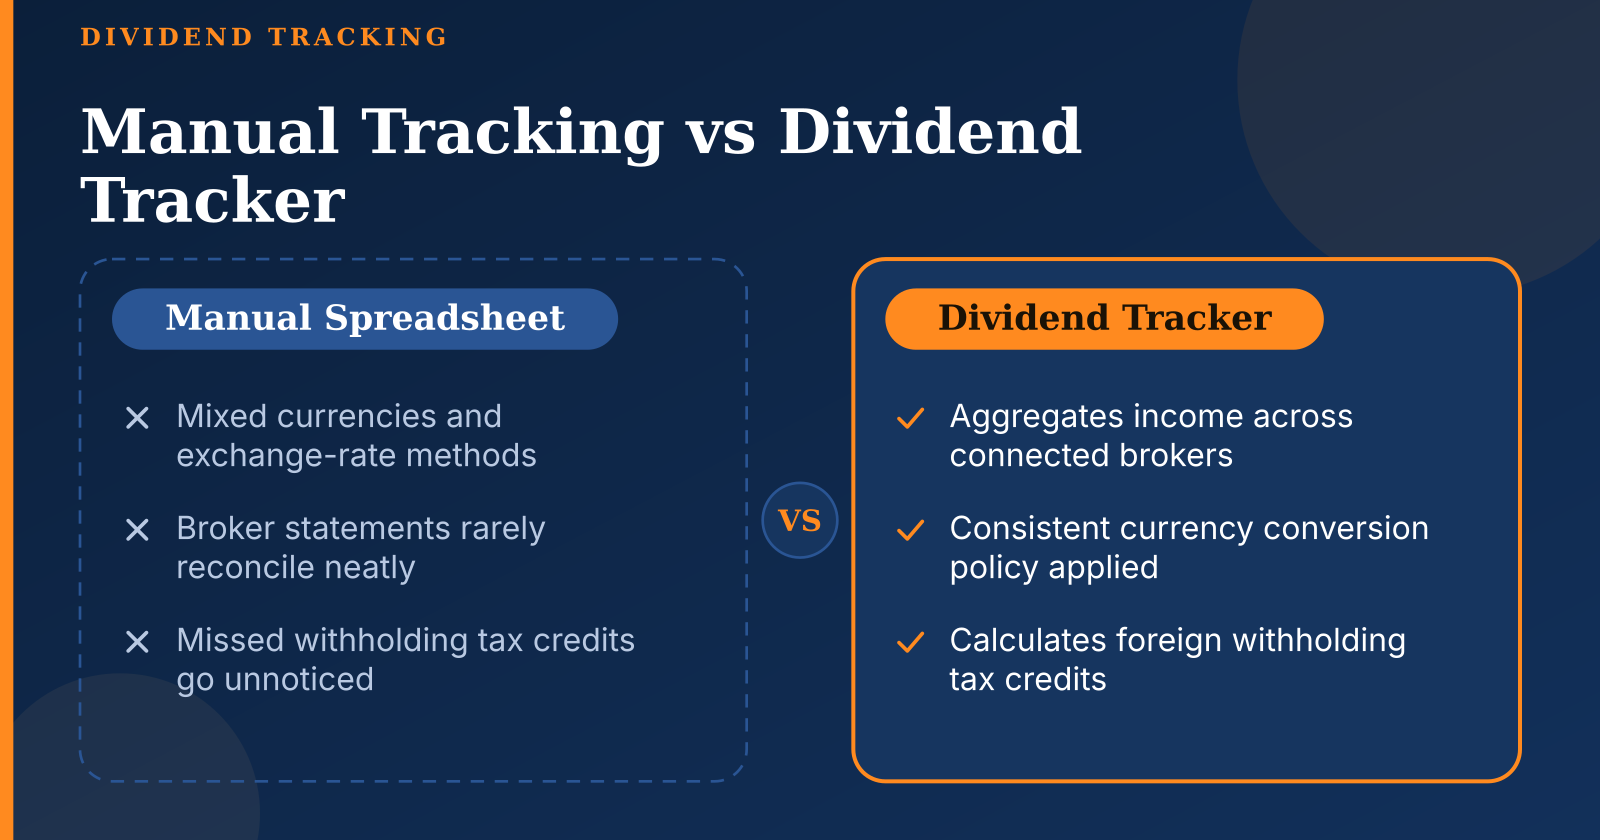
The practical value of automation shows up at filing time. Instead of reconstructing a year of payments from several broker statements, you have a per-country schedule of gross income, foreign tax withheld, and the credit calculated against the Czech liability. That schedule is far easier to check, and far easier to defend if a question is raised later.
Choosing a Dividend Tracking Solution: Criteria That Matter
When evaluating a tracker, begin with data coverage. Count the brokers it supports and find out whether imports are automated through an API or depend on file uploads, since the latter means ongoing manual work. Check how it handles non-US markets, American depositary receipts, and funds, because the treatment of these instruments often reveals how thoroughly the tool was built. Ask specifically how it deals with brokers that report withholding inconsistently, since that is where errors most often hide.
Next, examine the tax logic. A tracker that only totals payments is useful for budgeting but leaves the tax work untouched. Verify that the tax features match your own residence and the countries where your holdings are domiciled, since a feature designed for one jurisdiction may not transfer.
Finally, look at transparency and control. A tool that presents polished totals but does not let you see behind them asks you to trust it blindly, which is a poor position to be in when the figures carry tax consequences.
Conclusion: Keeping Dividend Income Accurate and Defensible
Dividend income is easy to receive and surprisingly hard to track once it is spread across brokers, currencies, and tax jurisdictions. For Czech tax residents, the foreign withholding tax credit adds a further requirement: each payment must be linked to its source country, the applicable treaty rate, and the Czech liability it offsets, with documentation to support every figure.
A dividend tracker that handles these tasks turns a recurring headache into a reliable record. Tools such as Veverio approach this by consolidating income from connected brokers and calculating the credits automatically, which is most useful when you hold dividend-paying stocks and ETFs in several places. If the answer is yes, your dividend income is not just tracked but properly understood.