Backdoor Roth IRA Form 8606 Pro-Rata Aggregation (IRC § 408(d)(2)) & 2026 IRS RMD Table III Factors
EastCorp Capital Quantitative Desk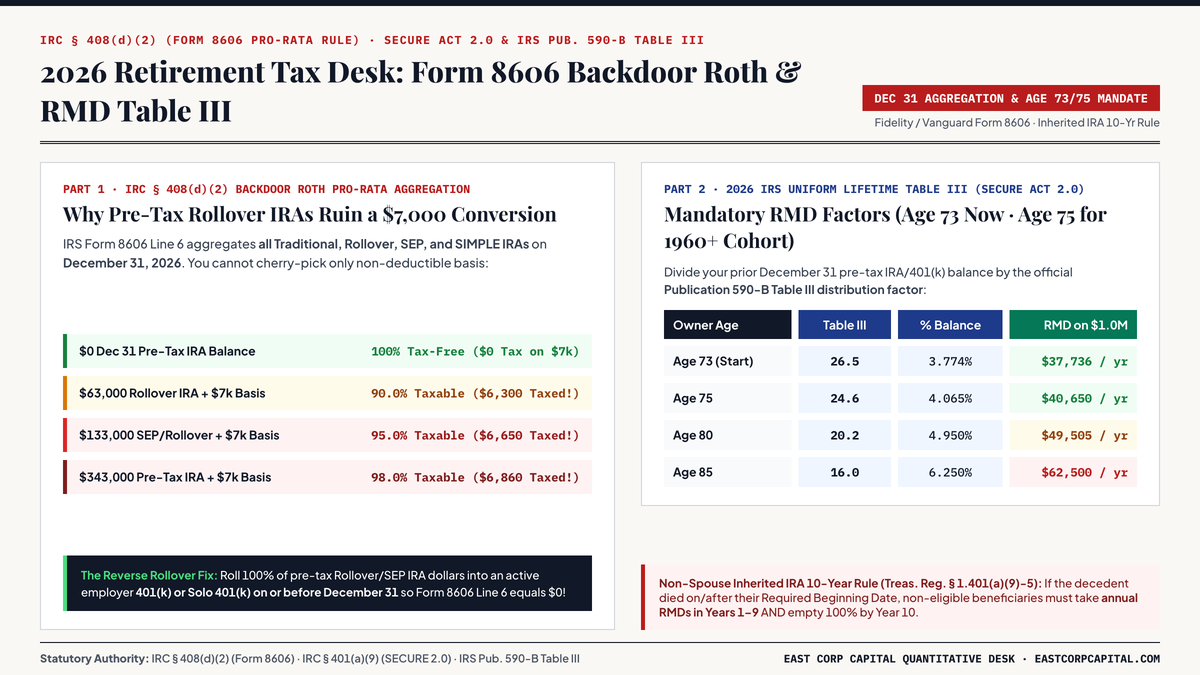
Executive Abstract: High-income executives executing a Backdoor Roth IRA conversion ($7,000 limit, or $8,000 if age 50+) frequently trigger unexpected ordinary income taxes because IRC § 408(d)(2) aggregates all non-Roth IRAs (Traditional, Rollover, SEP, and SIMPLE IRAs across all brokerages) as of December 31 of the conversion year. Later in life, SECURE Act 2.0 mandates Required Minimum Distributions (RMDs) starting at age 73 (rising to age 75 in 2033) under IRS Publication 590-B Uniform Lifetime Table III, alongside strict annual RMD rules inside the 10-year window for non-spouse Inherited IRAs.
1. Eliminating the Form 8606 Line 6 Pro-Rata Trap via a Pre-December 31 Reverse 401(k) Rollover
Under IRS Form 8606 Part I, the tax-free percentage of any Roth conversion equals Total Non-Deductible IRA Basis divided by the sum of (1) the conversion amount plus (2) the December 31 fair market value of all Traditional, Rollover, SEP, and SIMPLE IRAs (Line 6). If a taxpayer holds $63,000 in an old 401(k) Rollover IRA at Fidelity or Vanguard and contributes $7,000 of non-deductible basis to convert to a Roth IRA, 90% ($6,300) of the conversion is taxed as ordinary income.
Because employer 401(k), Solo 401(k), and 403(b) plans are excluded from IRC § 408(d)(2) aggregation, rolling the $63,000 pre-tax Rollover IRA into an active 401(k) plan on or before December 31 resets Form 8606 Line 6 to $0—making the entire $7,000 Backdoor Roth conversion 100% tax-free. Model your exact Form 8606 and RMD math below:
- Backdoor Roth IRA Step-by-Step Guide & IRS Form 8606 Pro-Rata Calculator — Canonical calculator & statutory verification (https://eastcorpcapital.com/backdoor-roth-ira-step-by-step-guide-fidelity-vanguard-irs-form-8606-2026/)
- Interactive 401(k) & Backdoor Roth IRA Form 8606 Simulator — Canonical calculator & statutory verification (https://eastcorpcapital.com/calculators/401k-roth/)
- Roth Conversion Ladder & Medicare IRMAA Surcharge Cliff Calculator — Canonical calculator & statutory verification (https://eastcorpcapital.com/calculators/roth-conversion-tax-irmaa-ladder/)
2. 2026 IRS Uniform Lifetime Table III RMD Factors (Age 73 = 26.5) & Inherited IRA 10-Year Rules
For account owners reaching age 73 in 2026 (born in 1953), the initial IRS Table III distribution period factor is 26.5 (3.7736% of the prior December 31 balance, or $37,736 on a $1,000,000 IRA), stepping down to 24.6 at age 75 (4.0650%), 20.2 at age 80 (4.9505%), and 16.0 at age 85 (6.2500%). Under final Treasury regulations (Treas. Reg. § 1.401(a)(9)-5), non-spouse beneficiaries who inherit an IRA from a decedent who had already reached their Required Beginning Date must take annual life-expectancy RMDs in Years 1 through 9 and liquidate 100% of the remaining balance by December 31 of Year 10.
Calculate your exact 2026 RMD, Inherited IRA 10-year schedule, and Qualified Charitable Distribution (QCD) offsets:
- 2026 RMD Calculator: IRS Uniform Lifetime Table III & Inherited IRA 10-Year Rule — Canonical calculator & statutory verification (https://eastcorpcapital.com/rmd-calculator-2026-irs-uniform-lifetime-table-inherited-ira-10-year-rule/)
- Interactive RMD & Inherited IRA SECURE 2.0 Simulator — Canonical calculator & statutory verification (https://eastcorpcapital.com/calculators/rmd-inherited-ira-secure-2-calculator/)
Published by EastCorp Capital Quantitative Tax & Real Estate Desk. Full suite of 60 interactive statutory simulators available at https://eastcorpcapital.com/.